

EN
October 5, 2026
app-publishers
In the last decade, fintech has grown quickly. According to McKinsey1, in 2025 the industry generated about $650 billion in revenue, a +21% increase over the year before, and it’s projected to reach $2 trillion by 2030.
However, behind these figures there’s a practical challenge: many fintech revenue models depend on a small number of levers, and any new monetization strategy has to respect users' trust and clearly show how their money and data are handled.
In this article, we'll look at how fintech apps make money, and then walk through three alternative fintech monetization strategies that can add revenue without getting in the way of the experience: subscriptions, API monetization, and partner-funded rewards.
👀 Did you know that gamification can be the first step to better app engagement? Learn more here: How gamification can turn your fintech app into a daily app
Even though it may vary by product, most fintech apps make money from three main sources: interchange, interest, and transaction fees.
Interchange is the biggest one for card-issuing apps. Each time a user pays with a card, the merchant pays a fee that is shared between the card network, the issuing bank, and the fintech. Users never see it, which is a big part of why many fintechs can offer accounts with few or no fees. Chime is an example of this. The company reported that interchange and payment fees made up about two-thirds of its Q3 2025 revenue2.
Interest income comes from lending, buy-now-pay-later, and balances held on behalf of users. It can be lucrative at scale.
Transaction fees are charged for moving money, such as payment processing, transfers, and currency exchange. They grow with volume, which also means they feel pricing pressure as lower-cost payment options spread.
Because the core levers are tied to market conditions, many fintech companies are adding newer revenue streams alongside them.
Compared to other app categories, fintech apps have limited monetization opportunities, for two main reasons:
So it’s important to find a balance that is profitable for your business, but respects your users’ wish for privacy and transparency. That's where the three strategies below come in.
A growing number of fintech companies are tiering their services and now offer both a free plan and a premium one. For teams considering a paid tier, there are a few things to consider:
In an API monetization strategy, your product becomes a source of revenue. In other words, your company can give other organizations access to its financial capabilities through APIs and charge them for using those services.
A famous example of API monetization is PayPal Checkout: sellers integrate PayPal's payment capabilities into their online stores, and PayPal charges a fee for processing transactions made through its platform.
API monetization can work in multiple ways, but the most common ways to monetize are:
Like many other apps, fintech apps often have their own loyalty program. For example, they reward users for bringing a friend or for reaching a certain spending threshold. However, these loyalty programs are usually funded by the same company, which uses its budget to reward users.
Partner-funded rewards change who pays. In this case, a third party covers the reward because it wants something in return – such as a new customer or an install – and the user gets the value without the app giving up margin. Two models do this well in fintech.
A card-linked offer is a digital coupon that applies automatically when a user pays with an enrolled card: customers link their card to a program, retailers fund the rewards, and the reward is then applied automatically the next time customers use that card at a featured retailer.
Card-linked offers work as a monetization stream for fintech apps because fintech apps act as the publishers: they take care of surfacing the offers to their users and get a share of revenue for hosting CLOs.
👀 Learn more about card-linked offers here: Why card-linked offers (CLOs) work and how you can use them to monetize your app
A game-linked offer lets users earn rewards by installing and playing mobile games. The fintech app is still the publisher, and it integrates a gaming layer into its interface to surface mobile gaming titles. Users download the game and get rewarded for the time spent playing, while fintech apps get a share of revenue for every new install.
Unlike card-linked offers, game-linked offers don't depend on spending, so they can monetize users who rarely transact. So, the two models complement each other: card-linked offers monetize what users buy, and game-linked offers monetize their engagement between transactions.
If your fintech app has already integrated rewards, then partner-funded offers are a great monetization opportunity, because they allow you to fill the gaps with other revenue streams.
First of all, they monetize users who don’t subscribe to your premium plan, or who transact little, and they do it by giving them a clear benefit, such as a discount on a purchase or a reward for their engagement.
Second – and this is especially true for game-linked rewards – they can improve the engagement rate of your app because your app becomes a place of discovery. Instead of browsing for new games on the app stores, your users will turn to you because they know they’ll get rewarded for it.
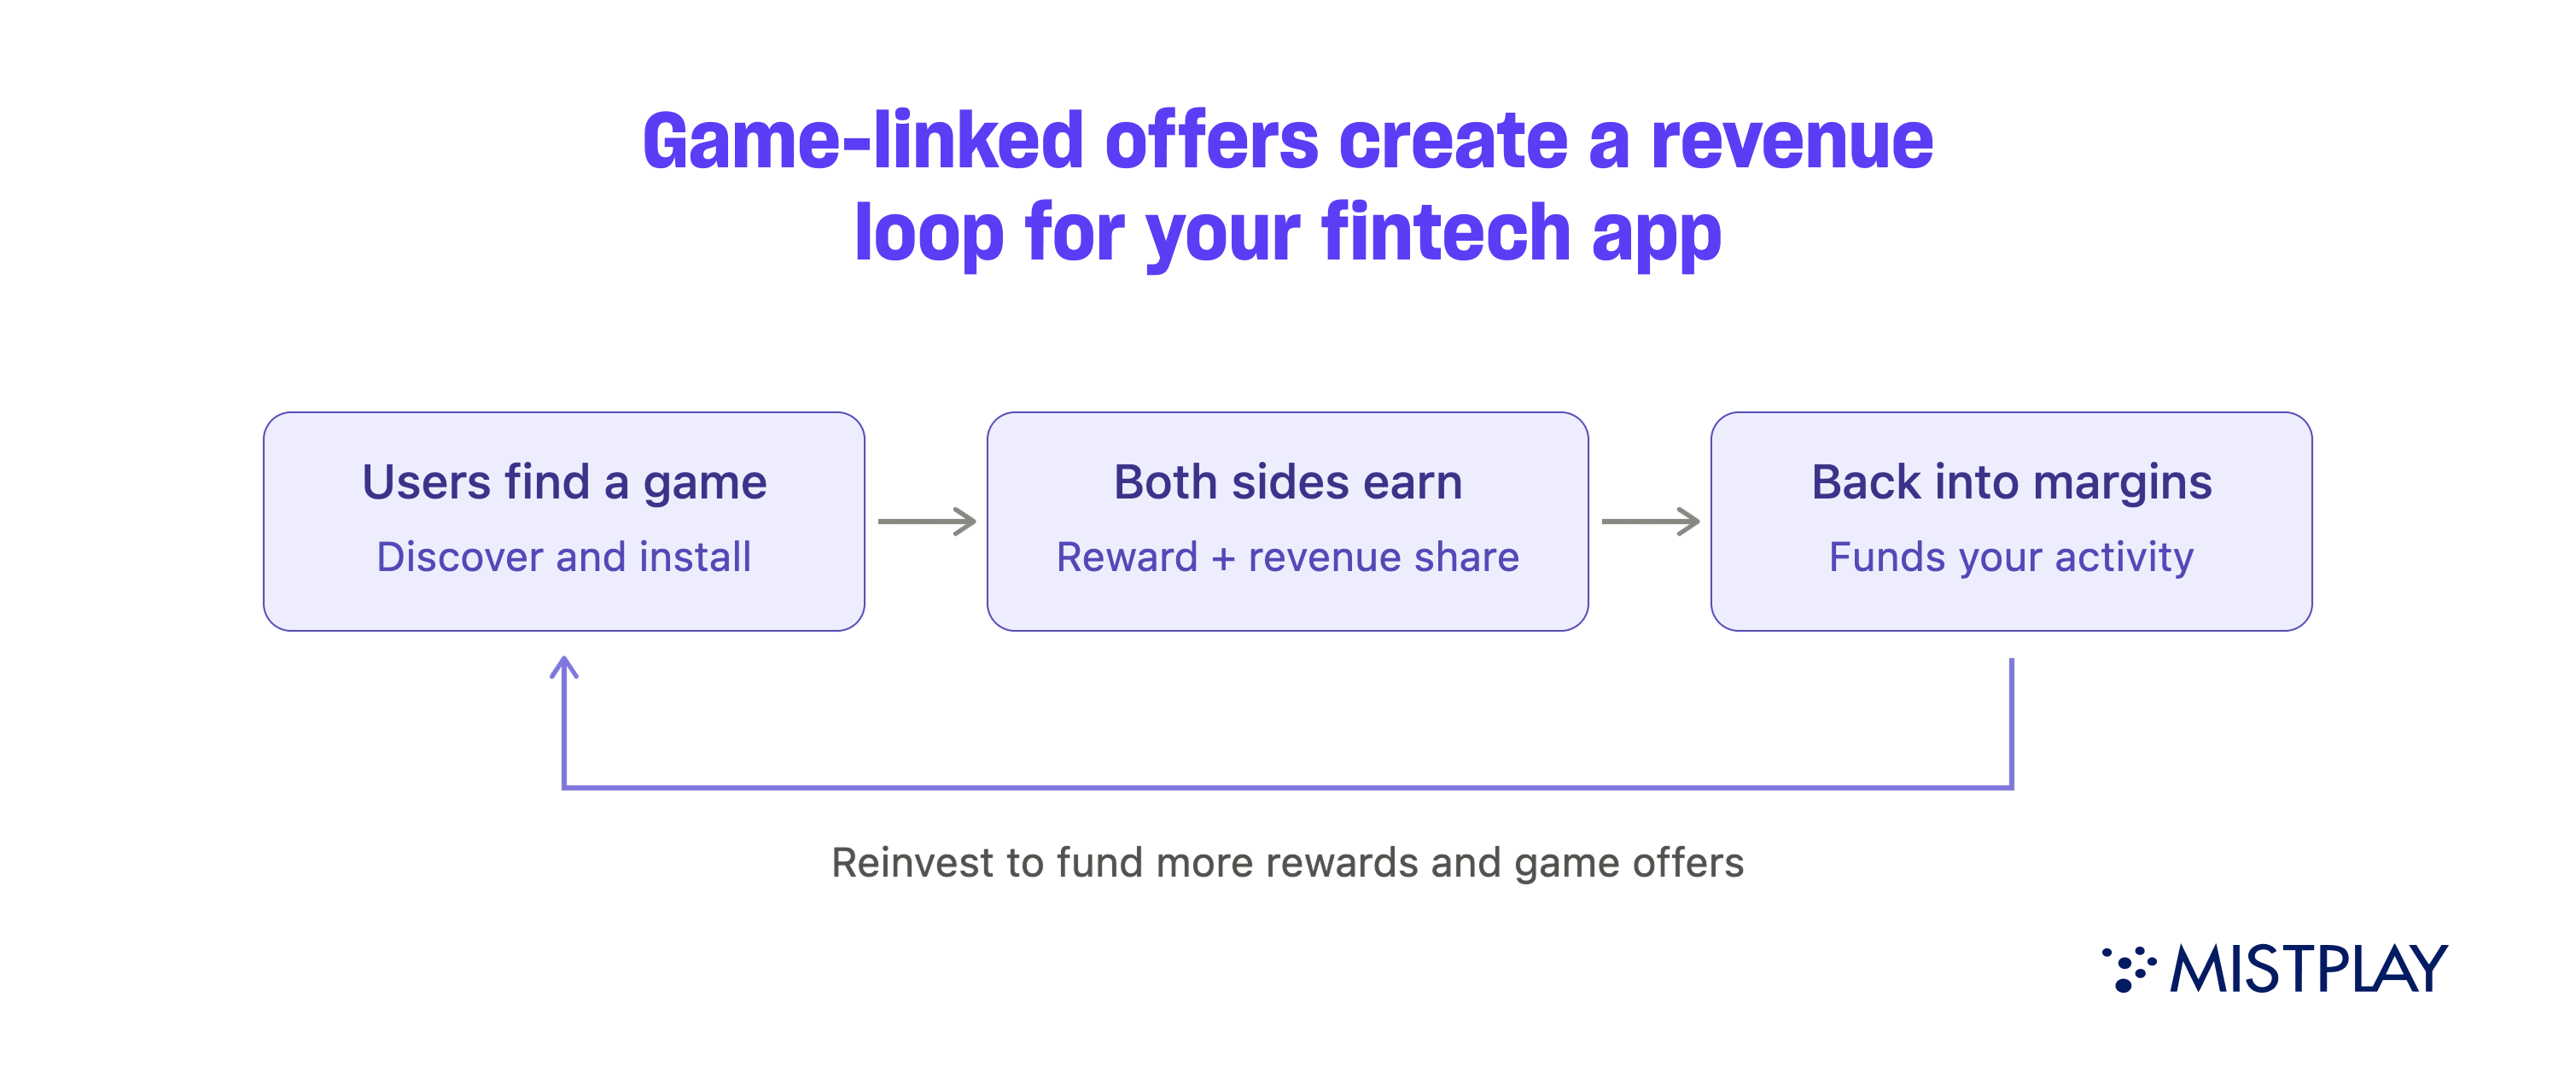
This creates a self-funding loop of revenue:
While fintech and mobile games may seem like two worlds apart, just know that 67% of US adults play mobile games weekly3. So that means that your users are likely already playing mobile games without being rewarded for it.
LoyaltyPlay, Mistplay’s rewarded gaming hub, was designed to help businesses from all industries to make the most out of this monetization opportunity. It layers onto your existing ecosystem and allows your users to earn rewards by playing a curated selection of mobile games.
Every time a user installs a game through your app, that action generates CPI-based revenue for you. This creates a revenue loop: the more users play, the more you earn and can reinvest directly into your business.
If you're curious to learn how LoyaltyPlay can fit into your current monetization strategy, reach out to us. Together, we can find the best solution for your business.
Sources